MT5 Quant Research Agent
An honest edge-discovery framework for MetaTrader 5 strategies.
Imports MT5/CSV data, applies real trading costs, and computes expectancy, PF, Sharpe/Sortino/MAR with walk-forward and Monte Carlo validation.
- Applies real spread, commission, and slippage before scoring
- Expectancy, PF, Sharpe, Sortino, and MAR metrics
- Walk-forward and Monte Carlo out-of-sample validation
- Live trading disabled by default
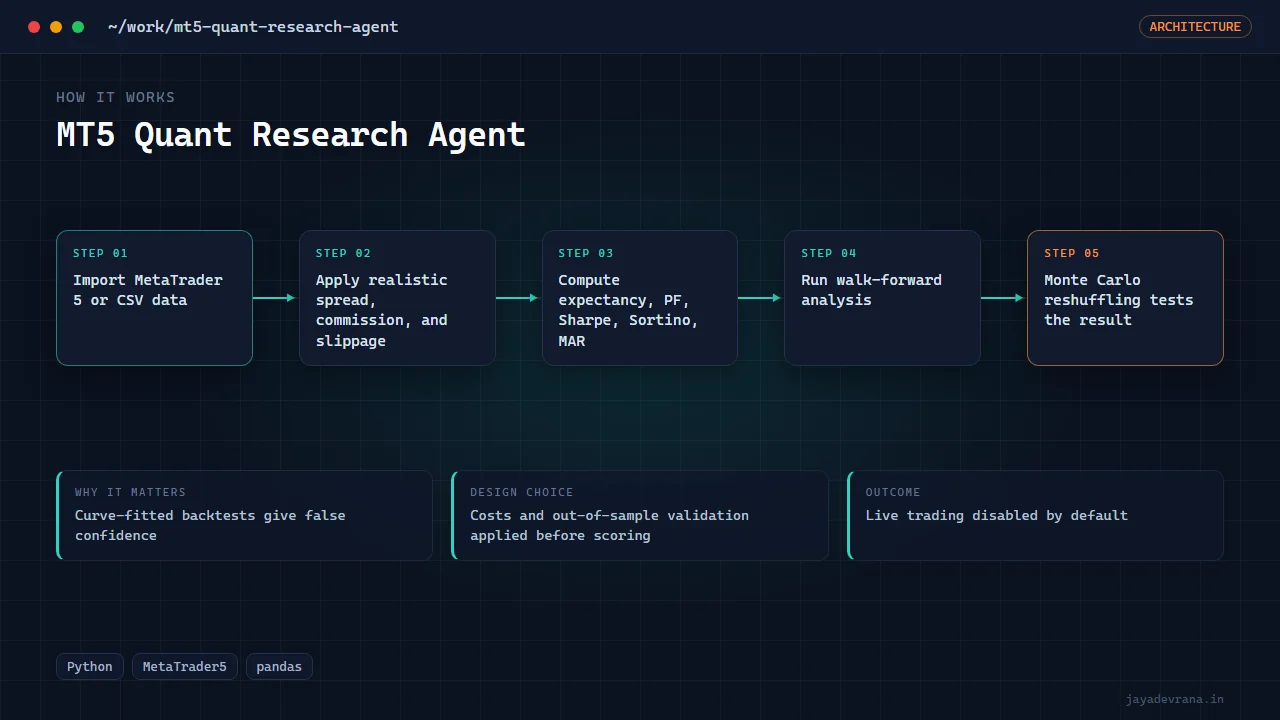
A research framework built around honesty rather than curve-fitted equity porn. It imports MetaTrader 5 or CSV data, applies realistic spread, commission, and slippage, and then computes the metrics that actually matter: expectancy, profit factor, Sharpe, Sortino, and MAR. Critically, it runs walk-forward analysis and Monte Carlo validation to test whether an apparent edge survives out of sample and reshuffling.
Live trading is disabled by default — the tool exists to find and stress-test edges, not to rush money into the market. It is the statistical-rigor backbone behind the EA work, the piece that decides whether a strategy is worth compiling into an Expert Advisor at all.
Research tooling only; past performance does not guarantee future results and nothing here is financial advice.
How it works
- Import MetaTrader 5 or CSV data
- Apply realistic spread, commission, and slippage
- Compute expectancy, PF, Sharpe, Sortino, MAR
- Run walk-forward analysis
- Monte Carlo reshuffling tests the result
Software and automation are infrastructure, not financial advice. No performance guarantees. Every live system needs staged testing, risk limits, and owner approval.